
Most bakeries don't lose money in one dramatic event. They lose it in slow, invisible slivers — a little extra butter here, a case of chocolate that walked out the back door there, a scale that's reading 40 grams light on every weigh-out. By the time it shows up in your monthly P&L, you're staring at a number you can't explain and three weeks too late to fix it.
The problem with most variance tracking is that it's built for accountants. It lives in spreadsheets nobody opens, reconciled monthly, and the person who actually touches the inventory — the morning manager — has no fast way to know if something's off today. So this post is about one thing only: a daily inventory micro‑audit your bakery can run in about three minutes, on your five or six highest-cost perishables, with tolerance bands, a short investigation script, and corrective actions you can take on the spot. No accounting degree needed. No month-end dread.
Why monthly reconciliation lets expensive variances hide
Here's the uncomfortable math. Butter, cream, chocolate, eggs, and vanilla probably make up 55–65% of your ingredient spend across maybe a dozen SKUs. Those are the items where a small percentage drift becomes real money fast.
If you only reconcile monthly, a variance has 30 days to compound before anyone sees it. A walk-in that's over-portioning cream by 8% doesn't look like anything on day one. Over a month it's a few hundred dollars gone — and worse, you've lost the context to figure out why. Was it Tuesday's new hire? The catering order that got double-prepped? The case that arrived short? Nobody remembers by the 31st.
The variances that actually hurt tend to be concentrated in a handful of items, and they almost always leave a same-day trail. Catch them the morning after and the cause is usually obvious. Catch them a month later and it's archaeology.
The whole point of a micro‑audit is to shrink that detection window from 30 days to 1.
Pick the five or six items that actually matter
Don't audit everything. That's the mistake that kills these systems — someone builds a 40-line daily count sheet, it takes 25 minutes, and it's abandoned inside two weeks. Your audit list should only include items that are high cost per unit AND easy to lose track of. A good filter:
Never miss a bake or delivery again.
Bakeryly helps you schedule, track, and manage every order effortlessly.
- Unified order tracking
- Real-time inventory alerts
- Staff shift management
No credit card required
-
High unit cost (butter, European chocolate, vanilla, nuts, cream)
-
Easy to over-portion or over-pour
-
Small, portable, theft-prone (vanilla, specialty chocolate, nuts)
-
Used across multiple products, so errors compound
For a typical café bakery that usually lands on something like: cultured butter, couverture chocolate, heavy cream, whole eggs, vanilla extract, and maybe one seasonal high-cost item (pistachio paste during the holidays, say). Five or six items. That's it.
Everything else can stay on your normal weekly or monthly count. If you're not sure which items deserve the daily slot, your usage forecasting work pairs well here — the method in forecasting ingredient demand for weekends vs weekdays gives you the expected-usage baseline the micro‑audit measures against.
The 3‑minute micro‑audit, step by step
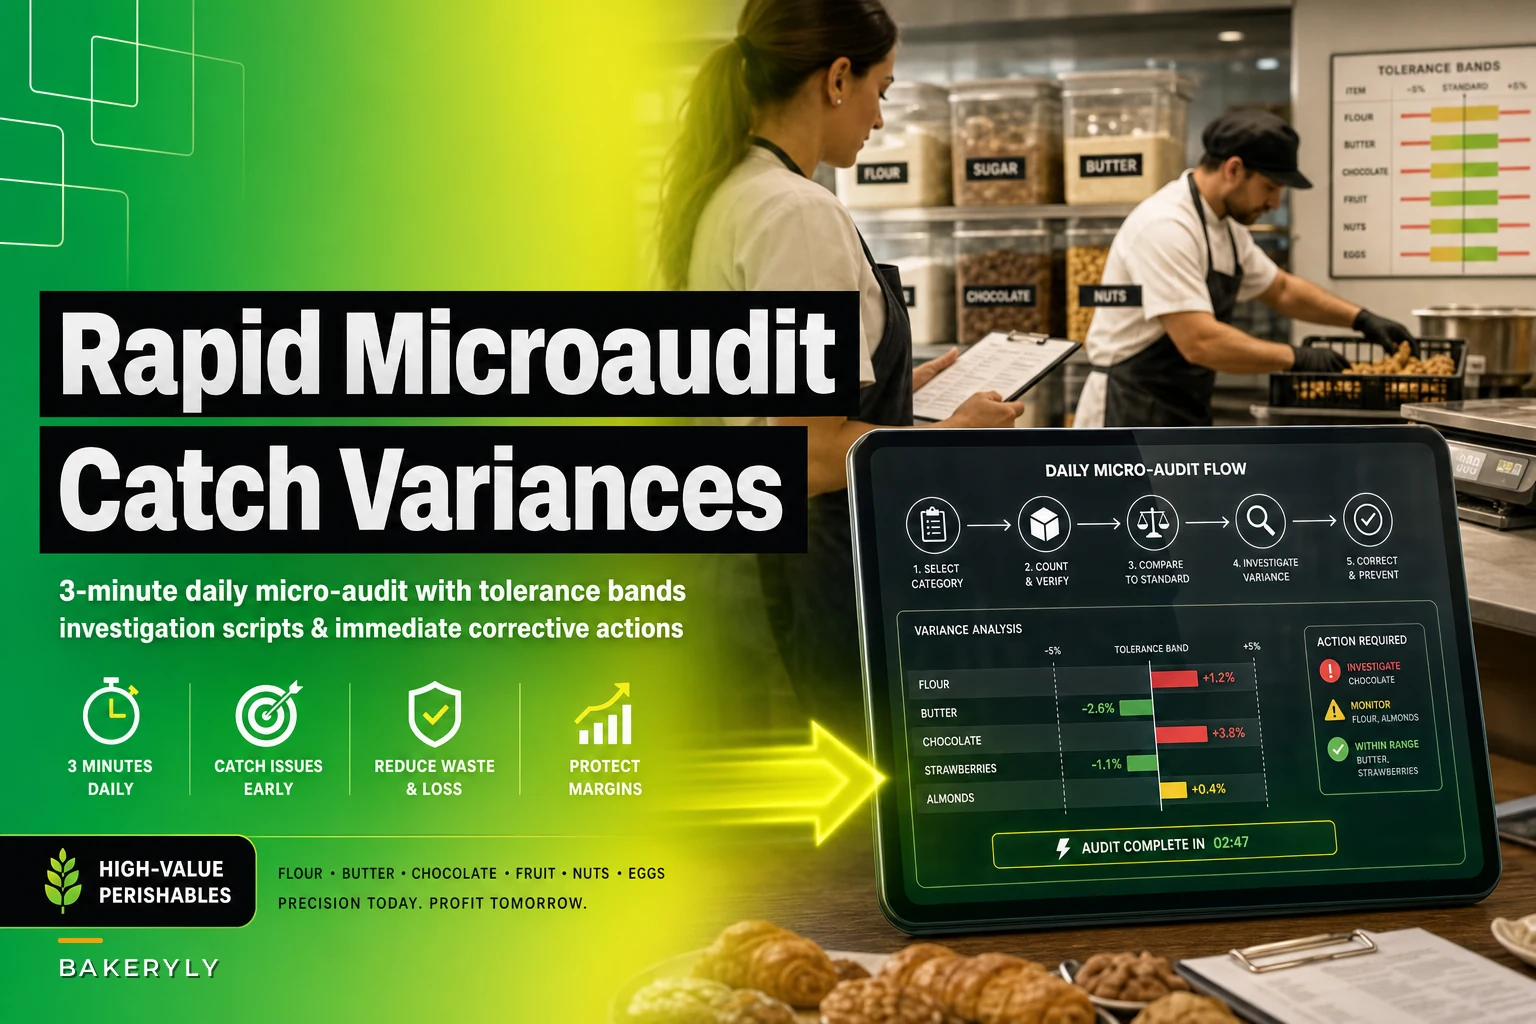
The audit compares what you should have used (based on yesterday's production) against what you actually used (measured by physical count). The gap is your variance. Tolerance bands tell you whether to shrug or investigate.
-
Pull yesterday's production count. How many croissants, how many chocolate tarts, how many batches of ganache. You already have this from your production log or POS.
-
Calculate theoretical usage. Production count × recipe quantity per unit. For butter: 180 croissants × 42g = 7.56 kg expected. Keep these multipliers on a laminated card so nobody's doing math from memory.
-
Read opening stock from yesterday's closing count. This is why the count has to happen daily — yesterday's close is today's open.
-
Count current physical stock. Quick weigh or case count on your five or six items only.
-
Compute actual usage opening + deliveries − current = actual used.
-
Compare actual vs theoretical. The difference, as a percentage, goes against your tolerance band.
-
If outside the band, run the investigation script (below). If inside, initial the sheet and move on.
Visual workflow of the micro‑audit.
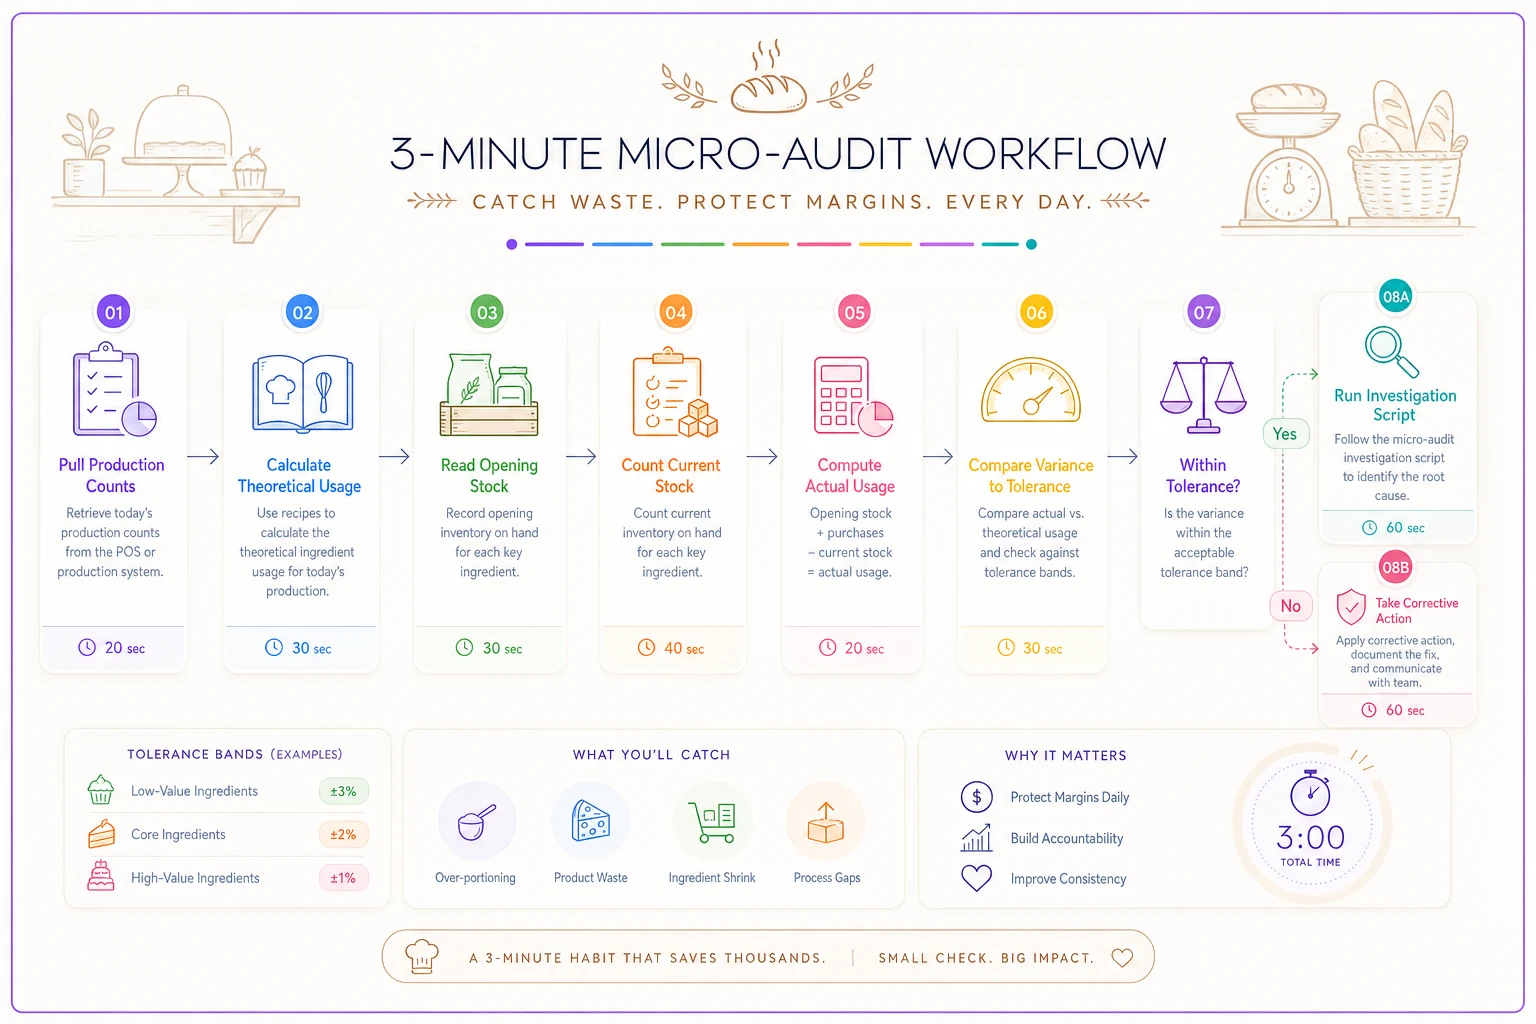
Once your opening numbers and recipe multipliers are set, steps 4 through 6 genuinely take about three minutes for six items. The first week feels slow. By week two it's muscle memory.
Setting tolerance bands so you're not chasing noise
Tolerance bands are the part everyone gets wrong. Set them too tight and the manager investigates normal variation every single day until they quit the process. Set them too loose and you miss the stuff that matters. A workable starting point — adjust to your own data after a couple weeks:
| Item type | Green (ignore) | Yellow (note & watch) | Red (investigate now) |
|---|---|---|---|
| Butter / cream (liquid/soft, portioned) | 0–3% | 3–6% | over 6% |
| Couverture chocolate | 0–2% | 2–5% | over 5% |
| Eggs (counted units) | 0–2% | 2–4% | over 4% |
| Vanilla / extracts | 0–2% | 2–4% | over 4% |
| High-cost seasonal (pistachio, saffron) | 0–2% | 2–4% | over 4% |
Why are the bands tighter on chocolate and vanilla than on butter? Because soft and liquid ingredients have genuine prep loss — scraping bowls, pan residue, normal waste — so a few percent is expected. Chocolate and vanilla should be close to exact, so a 5% gap on chocolate is a louder signal than 5% on butter.
One pattern worth flagging: a persistent yellow is often more dangerous than an occasional red. A single red is usually a one-off — a spill, a miscount. A SKU sitting in yellow for five days straight is a systematic leak: a mis-set scale, a recipe everyone's over-pouring, or slow shrinkage. Track the yellows over a week, not just the reds.
The investigation script (so the manager knows exactly what to do)
A variance alert is useless if the response is "huh, weird" and a shrug. The script has to be short enough to run at 6 a.m. and specific enough that anyone can follow it. When an item hits red:
-
Recount it first. Half of all reds are counting or math errors. Re-weigh, recheck yesterday's close, confirm the delivery was logged.
-
Check for unlogged production. Did someone make an off-book batch for a last-minute catering order? Staff meal? Samples? This is the single most common real cause.
-
Check for unlogged deliveries or returns. A case that came in late and never got added to opening stock shows up as "mystery usage."
-
Check the scale/portioning tool. Pull a known weight and verify. A drifting scale over-dispenses on every single pour and reads as steady overuse.
-
Check waste and damage log. Dropped tray, failed batch, spoiled case — all legitimate, all need to be written down.
-
If none of the above
flag for close attention tomorrow.
Two reds in a row with no explanation is when you look harder at handling, portioning habits, or theft.
Write the finding on the sheet in a word or two. "Scale off." "Catering batch." "Recount — fine." That note is what turns a pile of daily sheets into a diagnostic record you can actually read later.
Immediate corrective actions
Catching the variance is half the value. The other half is doing something that morning so it doesn't repeat. Match the cause to the fix:
-
Scale drift → recalibrate or swap the scale before production starts; recheck weekly.
-
Over-portioning → re-demo the correct portion with the staff member on shift, physically, not verbally.
-
Unlogged batches → tighten the production log so off-book batches get written down at the point they happen.
-
Delivery mismatch → confirm counts against the invoice at the dock, not after it's shelved. Short cases you never catch are pure margin loss.
-
Repeated unexplained shrink on portable items → move vanilla/specialty chocolate to a controlled shelf and log withdrawals.
What makes these stick is doing the correction before the first batch, not writing "fix later" on a sticky note that migrates to the floor by lunch.
A real scenario
A two-location café bakery kept noticing their couverture chocolate spend creeping up — somewhere around $600–$800 more per month than the recipes should've justified — but nobody could pin it down because counts only happened at month-end.
They started the micro‑audit on six items. Within the first week the chocolate sat in yellow four mornings straight, then popped red on a Saturday. The investigation script caught it fast: the ganache station was using a volume scoop instead of a scale, and the scoop was running roughly 10–12% heavy on every batch. During weekend volume that over-pour was real money.
Fixed it in about ten minutes — scale at the station, quick re-demo for the two people who worked that station. Chocolate variance dropped back into green the following week. The recovered margin landed somewhere around $500–$650 a month, and the "mystery" that had bugged them for a quarter turned out to be a $9 scoop.
That's the whole case for a daily window. The cause was obvious the morning after. It would've been invisible at month-end.
When this makes sense — and when it doesn't
This works best for bakeries where a small number of expensive perishables drive most of the cost, and where production volume is high enough that small drifts compound quickly. If you're running significant catering, wholesale, or weekend surges, the daily cadence pays for itself quickly.
When it's overkill: a very low-volume operation making a handful of items a day, with one owner who touches every ingredient personally, probably doesn't need a formal daily audit — you already are the audit. A weekly check is fine.
Who should not bother: anyone who won't actually run it daily. An inconsistent micro‑audit is worse than none, because the gaps in the data make every variance look like a counting error. If you can't commit to the three minutes every morning for at least a month, don't start — fix the consistency problem first.
Keeping it running past week three
These don't die because they're complicated. They die from drift. The count gets skipped on a busy Saturday, then two Saturdays, then it's gone. A few things keep it alive:
-
Tie it to an existing routine — right after opening temps, before first bake. Never a standalone task.
-
Keep the list to six items, hard cap. The moment it grows to fifteen, it dies.
-
Rotate who runs it so it's not one person's burden, but keep the sheet in one place so the record stays continuous.
-
Review the sheets weekly for yellows, not just reds. That's where the slow leaks live.
Tie it to an existing routine — right after opening temps, before first bake.
If you're already running digital production logs and reconciliation workbooks, the theoretical-usage math can be calculated automatically from production counts rather than by hand — which cuts the three minutes down further and removes the arithmetic errors that cause half your false reds. And if the bigger issue is that you don't yet have a basic cost-control foundation to measure against, the approach in stop margin erosion: a simple financial‑control system small bakeries can run without an accountant is the layer this micro‑audit sits on top of.
The micro‑audit isn't trying to replace your financials. It's an early-warning tripwire on the five or six items most likely to quietly drain your margin — close enough to the floor that the person who finds the problem is the same person who can fix it, that morning, before it costs you another month.
Ready to elevate your bakery operations?
Join 2,000+ bakeries using Bakeryly to streamline workflows, reduce waste, and delight more customers.